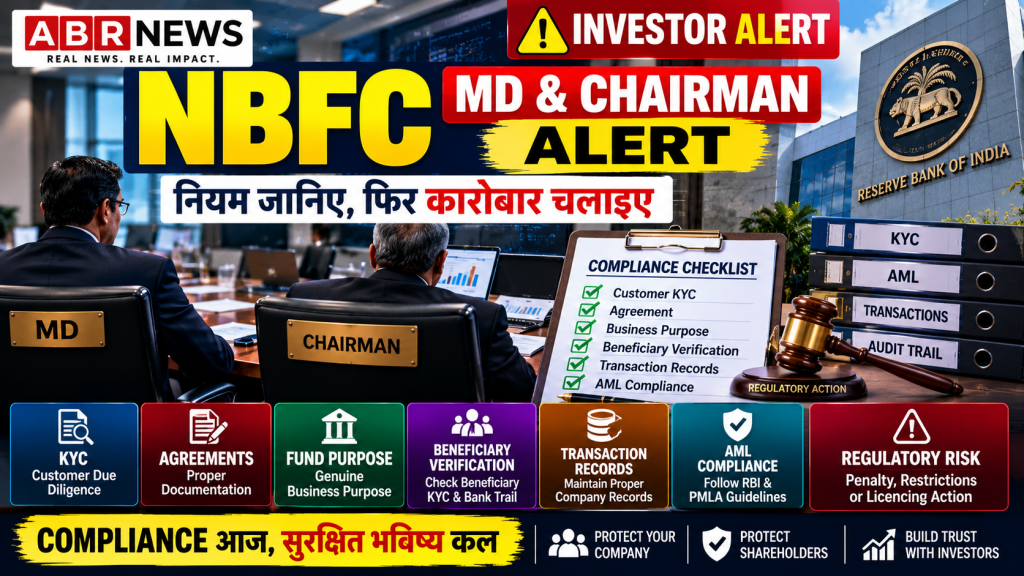
भारत में NBFCs को applicable KYC, customer due diligence,
AML और transaction-monitoring requirements का पालन करना होता है।
अगर किसी NBFC द्वारा ऐसे transaction या loan disbursement का मामला सामने
आता है जिसमें required KYC/CDD का पालन नहीं हुआ, तो circumstances के आधार
पर regulatory scrutiny और enforcement action का सवाल उठ सकता है।
⚠️ INVESTOR ALERT
सिर्फ KYC deficiency अपने-आप money laundering साबित नहीं करती।
लेकिन unexplained fund flow, suspicious beneficiaries या proceeds of crime
से connection सामने आए तो मामला अधिक गंभीर हो सकता है।
1️⃣ RBI Monetary Penalty
KYC और regulatory compliance में deficiencies पाए जाने पर RBI,
applicable statutory powers के तहत NBFC पर
monetary penalty लगा सकता है। Penalty की रकम और nature
actual violation तथा applicable provisions पर निर्भर करती है।
Related Sources:
Source 1 |
Source 2 |
Source 3
2️⃣ Business Restrictions
Serious या continuing regulatory deficiencies की स्थिति में regulator
applicable powers के तहत NBFC के कुछ business operations पर restrictions
लगाने जैसे supervisory measures पर विचार कर सकता है। यह
automatic consequence नहीं है और प्रत्येक मामले के facts
पर निर्भर करता है।
Possible regulatory concerns:
Customer onboarding • Loan disbursement • KYC/CDD •
Transaction monitoring • Record keeping • Fund utilisation
3️⃣ NBFC Certificate of Registration पर Action
गंभीर statutory non-compliance में RBI के पास applicable law के तहत
NBFC के Certificate of Registration (CoR) से संबंधित
regulatory action लेने की powers हो सकती हैं। हालांकि केवल एक disputed
transaction से licence cancellation automatic नहीं होता।
4️⃣ Money Laundering Trail मिले तो ED Investigation
अगर जांच में यह material सामने आता है कि transactions का संबंध
proceeds of crime से है और PMLA के आवश्यक statutory
elements मौजूद हैं, तो Enforcement Directorate (ED)
की investigation relevant हो सकती है।
🔎 FUND TRAIL
Source of Money → Customer KYC → NBFC Account →
Bank Transfer / RTGS → Beneficiary Account →
Further Transfer → Ultimate Beneficiary
Investigation में bank statements, UTR numbers, KYC records,
loan agreements, company ledger, beneficiary information और electronic
communications महत्वपूर्ण evidence बन सकते हैं।
5️⃣ Bank Accounts Freeze हो सकते हैं?
Financial/cyber-crime investigation में relevant accounts या funds के
खिलाफ freezing/restraint की कार्रवाई competent authority द्वारा
applicable statutory procedure के तहत की जा सकती है।
सिर्फ KYC deficiency मिलने से हर account automatically freeze नहीं होता।
Related Sources:
Account Freeze Source 1 |
Account Freeze Source 2
🚨 NBFC Investor Alert: ये 8 Records सबसे महत्वपूर्ण
1. Customer KYC
2. Loan / Transaction Agreement
3. Bank Statement
4. RTGS / UTR Number
5. Beneficiary KYC
6. Company Ledger Entry
7. Purpose of Payment
8. Ultimate Utilisation / Beneficiary Trail
अगर किसी NBFC transaction पर सवाल उठता है, तो केवल यह देखना पर्याप्त नहीं
है कि पैसा account से गया। महत्वपूर्ण सवाल यह है कि
किस customer के लिए, किस agreement के तहत, किस purpose से,
किस beneficiary को और company books में किस accounting treatment के साथ
payment किया गया।
🚨 ABR NEWS PUBLIC & INVESTOR ALERT
यदि किसी NBFC से जुड़े transaction में KYC, agreement या fund purpose
पर सवाल हों, तो निष्कर्ष निकालने से पहले
bank statement, UTR, customer KYC, beneficiary KYC,
agreement और ledger trail की independent verification जरूरी है।
Additional References
KYC / NBFC Reference 1
KYC / NBFC Reference 2
Legal Action Reference
Disclaimer: यह article regulatory और public-awareness
purposes के लिए है। KYC deficiency अपने-आप fraud, money laundering या
criminal liability साबित नहीं करती। किसी NBFC, director या अन्य व्यक्ति
के खिलाफ liability competent regulator, investigating agency या court
द्वारा evidence और applicable law के आधार पर निर्धारित की जाती है।